The selling pressure in global markets intensified after the US monthly inflation rose within expectations by 0.6%, while the annual inflation accelerated above estimates by 3.7%.
While the US inflation hit a five-month high month-on-month, the annual inflation reached its highest in four months, according to the Bureau of Labor Statistics on Wednesday.
These developments fueled the US Federal Reserve’s hawkish expectations.
At the same time, gas prices jumped 9.1% over the month, making up more than half of the overall monthly increase of consumer inflation.
The US’ core consumer price index (CPI), excluding energy and food prices, rose 0.3% month-on-month and 2.6% on an annual basis, above estimates.
Richmond Fed President Tom Barkin said the US CPI figures exceeded his expectations and that the producer price index (PPI) to be released on Thursday will help assess the inflation outlook, while refusing to speculate on the Fed’s policy roadmap for this month.
Chicago Fed President Austan Goolsbee said the September CPI was “discouraging,” while the service inflation was also causing concerns, noting that it remains unclear how the Fed will assess the current situation, faced with a strong economy but high inflation.
Meanwhile, the Fed’s Beige Book showed that price pressures remained and intensified in some regions of the US.
Markets expect the Fed to cut rates this month with a 73% probability, up from 22%, given the recent developments.
Tech stocks tumbled with growing hawkish expectations amid accelerating inflation, coupled with concerns over artificial intelligence (AI) investment profitability, while rising oil prices due to the developments in the Middle East fueled concerns that central banks may need to be tighter on monetary policy.
The US 10-Year Treasury bond yield dropped nine basis points to 5.11%, and the US dollar depreciated 0.2% to 102.1.
December-delivery Brent crude oil declined 1.7% to $104.3 a barrel following reports that US President Donald Trump is considering easing sanctions on ships transporting oil and petroleum products from sanctioned countries like Russia, Iran, and Venezuela.
Gold climbed 1% to $4,145 per ounce as bond yields and the US dollar fell, alongside continued central bank purchases.
At the same time, the global oil demand is expected to fall by 2.5 million barrels per day in the fourth quarter compared to the same period last year, and by an average of 2.6 million barrels per day for the entire 2026, according to the International Energy Agency’s September report.
Some Russian oil refineries were brought back online following repairs, while conditions at the plants improved in recent weeks, Russian deputy prime minister said.
US banks also continued releasing their third-quarter earnings.
Morgan Stanley’s profit and revenue came in better than expected, but its shares closed Wednesday down nearly 3%.
Bank of America saw its third-quarter profit fall 17% to $6.9 billion following a $1.2 billion fine, while its shares lost around 5% and its profit and revenue reports did not meet expectations.
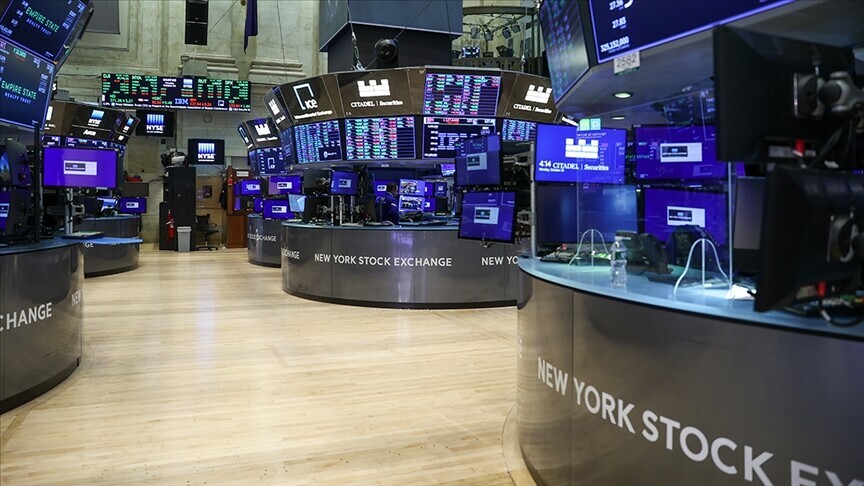
The Dow Jones Industrial Average fell 0.09%, the S&P 500 declined 1.11%, and the Nasdaq Composite was down 1.88% on Wednesday. American indexes started Thursday on a negative trend.
Meanwhile, European stock markets traded on a mostly positive trend as corporate earnings exceeded expectations.
Dutch semiconductor firm ASML’s shares rose 1.2% after it raised its forward-looking guidance with expectations that the strong AI demand would continue.
Defense firm Renk’s shares jumped 2.7% following a new order worth €130 million ($145.9 million) from tank-maker KNDS.
Chipmaker Infineon closed Wednesday down 1.7% amid an industry-wide selling pressure.
Attention turned to the meetings in Brussels, where EU leaders will address global economic imbalances on Thursday.
In light of these developments, Germany’s DAX 40 rose 0.15%, the UK’s FTSE 100 grew 0.7%, and France’s CAC 40 was up 0.58%, while Italy’s FTSE MIB 30 fell 0.61% on Wednesday. European indexes started Thursday on a negative trend.
Near Thursday’s close, Asian equity markets sharply declined due to a selling pressure on tech stocks.
SK Hynix shares lost 10.2%, Samsung Electronics dropped 8.6%, LG Innotek fell 9.2%, and Kioxia declined 11.3%.
Japan’s industrial production fell 2.4% on a monthly basis, while rising 2.7% year-on-year, both below expectations.
Near the close of trading, South Korea’s Kospi fell 7%, Japan’s Nikkei 225 declined 4.5%, Hong Kong’s Hang Seng decreased 1.5%, and China’s Shanghai Composite was down 2%.