Necva Tastan Sevinc
08 October 2026•Update: 08 October 2026
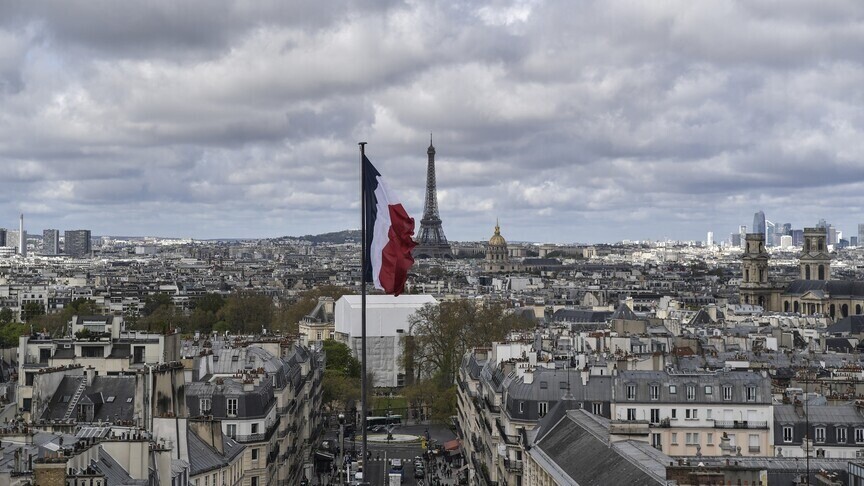
France’s Council of Economic Analysis urged policymakers to reduce the public deficit by €125 billion ($140 billion) by 2032 and overhaul public policies, Le Monde reported Thursday.
All 23 members of the council, which advises the prime minister, signed its first collective note since 2014, warning that policies pursued over the past three decades had become unsustainable.
The economists identified population aging, deteriorating public finances, weak productivity growth and declining educational performance as major challenges, alongside rising poverty and wealth inequality.
They warned that higher interest rates could trigger an uncontrolled increase in public debt, forcing France to repair its finances urgently on terms it could no longer determine.
The council recommended achieving roughly half the proposed deficit reduction during the first two years to restore market confidence and stabilize debt within five years.
Drawing on previous reports, it outlined 150 possible measures, including freezes on central and local government spending, changes to pension indexation, higher taxes and reductions in business subsidies.
The options include restoring housing or wealth taxes and raising value-added and corporate taxes.
The economists also proposed scaling back research tax credits to limit windfall benefits for large companies.
They argued that the adjustment could not fall mainly on a small section of the population or depend on uncertain future growth.
Alongside fiscal consolidation, the council called for €4 billion in additional annual investment in schools, wider adoption of digital technologies and artificial intelligence, and a “France 2040” innovation program.
It also urged stronger climate adaptation measures and higher taxation of large inheritances to address inequalities linked to inherited wealth.
The appeal comes seven months before France’s 2027 presidential election.